Quarter Ending September 30, 2026

Published first week of each month: A deeper dive into economic trends, investment strategies, and what it all means for your financial plan.

Strong Moves in Few Sectors Overcome Weakness Elsewhere

Surging bond yields and mixed equity returns were the headlines of the third quarter. The Nasdaq turned in the strongest quarter, but breadth was weak, and other areas of the market came under pressure. Concerns about ongoing military action in the Middle East, higher oil prices, accelerating inflation, and the Federal Reserve’s first rate increase in nine months gave investors plenty to navigate over the quarter.

Monthly Quick Hits

Beyond the Headlines

Strong Moves in Few Sectors Overcome Weakness Elsewhere

Fixed Income Update

Surging Bond Yields Dominate Fixed Income Markets

Geopolitical and Economic Update

Middle East, Strong Data Lead to 20-Year Highs in Yields

Looking Ahead

Fundamentals Remain Key


Beyond the Headlines:

Strong Moves in Few Sectors Overcome Weakness Elsewhere

Equity investors had a lot to digest in the third quarter. Negotiations to end the war in the Middle East and reopen the Strait of Hormuz deteriorated, leading to higher oil prices. In addition, accelerating inflation data, stronger economic data, and a Fed rate increase led U.S. Treasury yields to surge. However, fundamentals remained strong as second-quarter earnings came in well above analyst expectations.

Energy stocks’ reaction to a 30 percent increase in West Texas Intermediate crude prices and a rotation back to growth companies were the quarter’s positive market movers. The Nasdaq and the S&P 500 both moved higher. But breadth was weak, and the Dow Jones Industrial Average declined and the small-cap Russell 2000 dropped more than 7 percent. International developed markets were up slightly, and emerging markets declined marginally.

The energy sector rallied more than 16 percent on the strength of crude, while technology, health care, and communication services also recorded solid gains for the quarter. Given the surge in Treasury yields, higher-yielding equity sectors came under pressure, including utilities and real estate. Industrial stocks also came under pressure as enthusiasm for hyperscaler buildout waned.

Arrow up 2.61%

In the third quarter Nasdaq Composite

arrow up  2.30%

In the third quarter S&P 500

-2.34%

In the third quarter Dow Jones Industrial Average
Fixed Income Update:

Surging Bond Yields Dominate Fixed Income Markets

It was a difficult month for fixed income investors as continued energy supply disruptions led to higher oil prices and persistently higher inflation. Combined with stronger economic data, concerns about U.S. debt levels and the Fed embarking on a tightening cycle led to weakness across the Treasury curve.

Bond markets reacted to higher yields by selling off in lockstep. The Bloomberg U.S Aggregate Index dropped more than 3.5 percent for the quarter, and other areas like high-yield and municipal bonds followed suit. Yields are currently attractive for income investors, but headwinds will persist until a resolution in the Middle East reduces inflation pressure.

-3.51%

In the third quarter Bloomberg Aggregate Bond Index
 -1.82%

In the third quarter Bloomberg U.S Corporate High Yield Index

Geopolitical and Economic Update:

Middle East, Strong Data Lead to 20-Year Highs in Yields

With the U.S. and Iran unable to reach an agreement on ending the war and reopening the Strait of Hormuz, oil prices surged more than 30 percent, and once again began to spill into both consumer and producer inflation data.

At the same time, the employment market snapped back in August with 162,000 jobs created. The numbers of new jobs in June and July were also revised higher after weaker initial readings. This strength in hiring is indicative of a growing economy and gives the Fed more confidence to focus its policy decisions on inflation.

As a result, any hope the Fed would be able to reduce interest rates before year-end disappeared, and then flipped to expectations of multiple rate hikes. As sentiment on the Fed shifted, the bond market sold off. Treasury yields moved higher throughout the quarter, and the 10-year closed at the highest level since 2002.
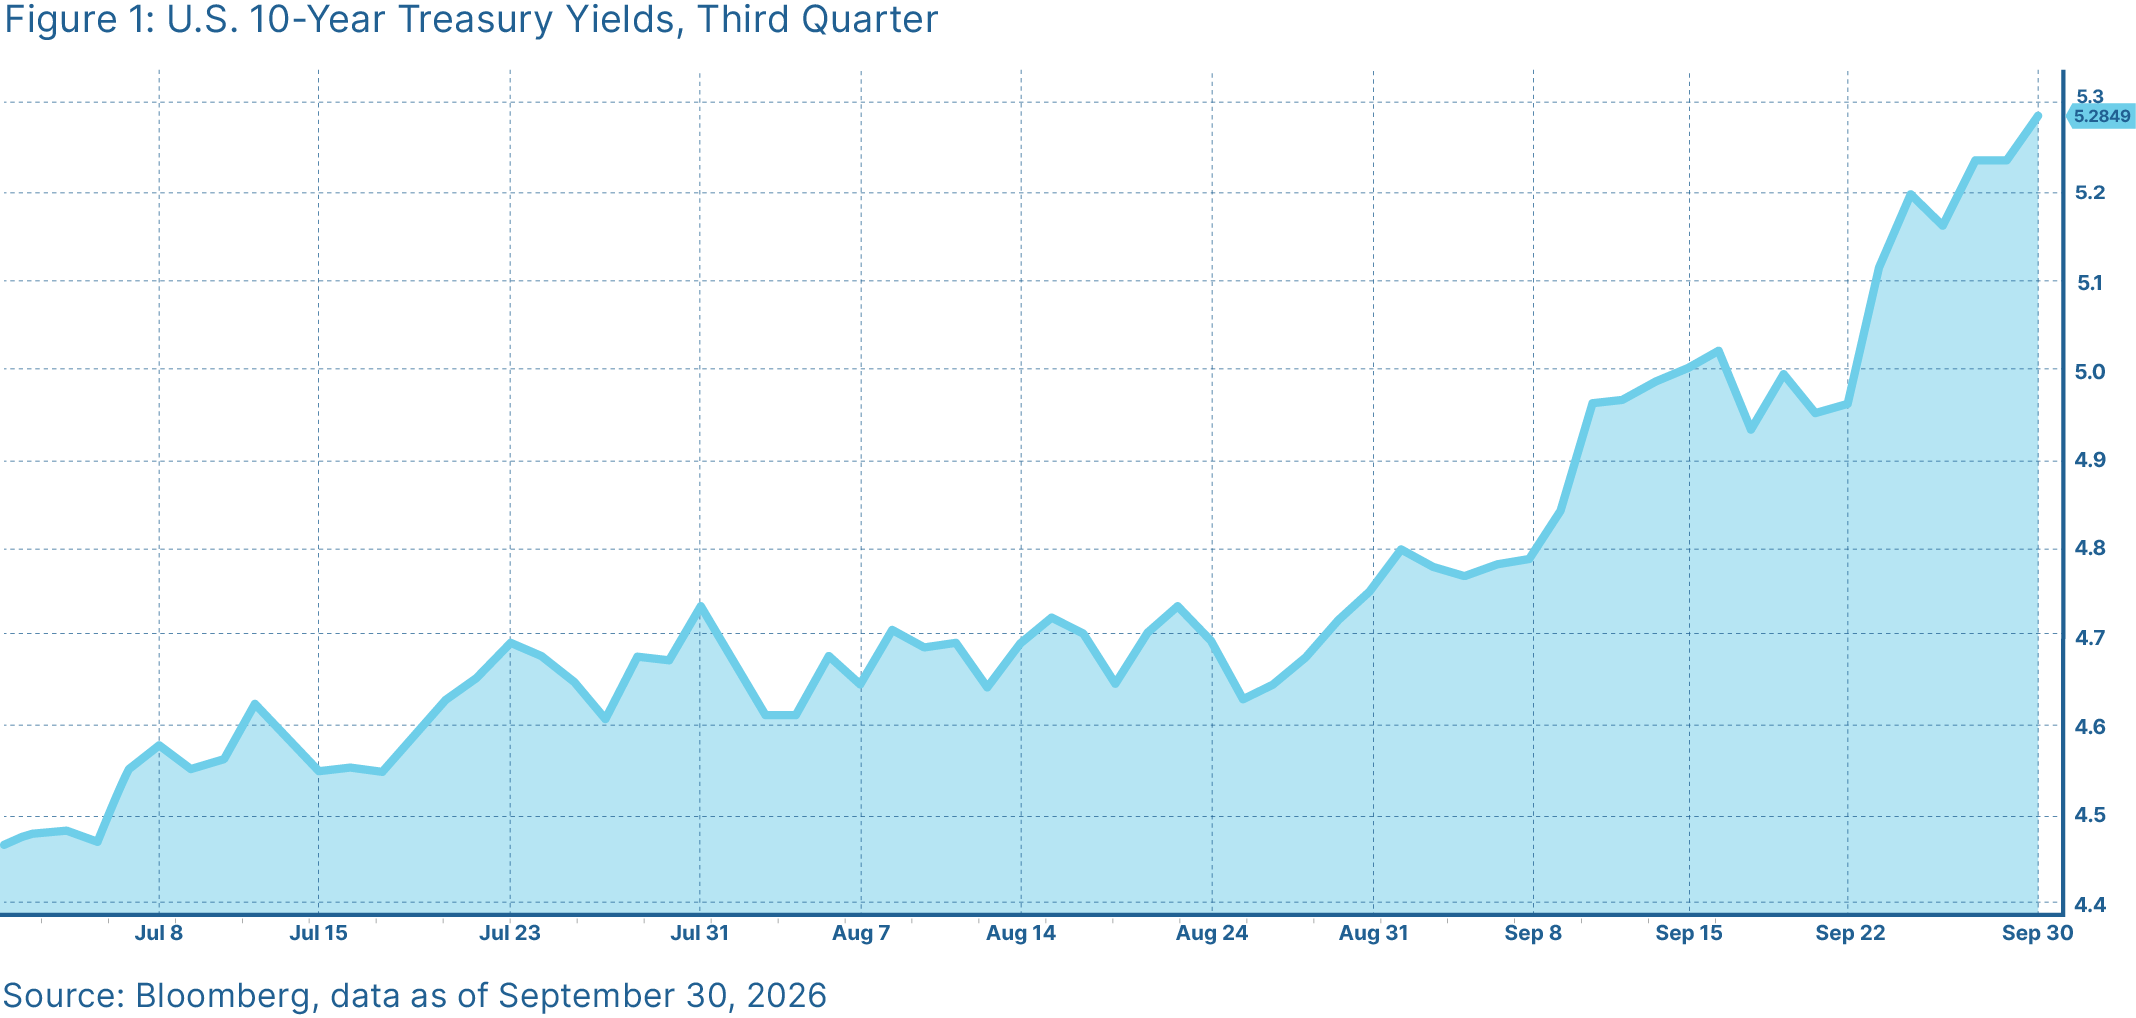
third quarter graph

Other factors are certainly weighing on fixed income investors, such as U.S. government debt crossing the $40 trillion level and artificial intelligence infrastructure spending leading to a stronger-than-expected economy. All combined, the bond market seems to be sending a message to the Fed that it needs to raise rates more aggressively to prevent the economy from overheating and inflation from moving higher.


The Takeaway


  • A deteriorating situation in the Middle East is leading to higher oil prices and higher inflation.
  • The Fed raised rates at its September meeting, and the bond market expects it to do more.


Looking Ahead:

Fundamentals Remain Key

As we turn our attention to the fourth quarter, there are three important topics worth watching:

  • The Middle East conflict and its impact on oil prices and inflation will continue to drive market movements and Fed policy.
  • Headlines about the coming election are prevalent and likely to continue through Election Day. This could lead to short-term movements in markets.
  • Earnings season will begin soon, and analysts expect third-quarter earnings will increase more than 29 percent. If this were to hold, it would mark the third straight quarter of earnings growth of more than 25 percent.

Fundamentals drive markets over the long term, and they remain relatively solid for now. Solid jobs growth, continued consumer spending, and strong earnings growth, we believe, should lead to economic growth and further market appreciation.

Risks continue to exist and need to be monitored. As a result, short-term market volatility is possible. However, a diversified portfolio that matches long-term goals and risk tolerance remains the best path forward. If concerns remain, however, speak to your financial advisor to go over your financial plans.

Disclosure: This material is intended for informational/educational purposes only and should not be construed as investment advice, a solicitation, or a recommendation to buy or sell any security or investment product. Please contact your financial professional for more information specific to your situation.

Certain sections of this commentary contain forward-looking statements based on our reasonable expectations, estimates, projections, and assumptions. Forward-looking statements are not guarantees of future performance and involve certain risks and uncertainties, which are difficult to predict. Past performance is not indicative of future results. Diversification does not assure a profit or protect against loss in declining markets. All indices are unmanaged and investors cannot invest directly into an index. The Dow Jones Industrial Average is a price-weighted average of 30 actively traded blue-chip stocks. The S&P 500 Index is a broad-based measurement of changes in stock market conditions based on the average performance of 500 widely held common stocks. The Nasdaq Composite Index measures the performance of all issues listed in the Nasdaq Stock Market, except for rights, warrants, units, and convertible debentures. The MSCI EAFE Index is a float-adjusted market capitalization index designed to measure developed market equity performance, excluding the U.S. and Canada. The MSCI Emerging Markets Index is a market capitalization-weighted index composed of companies representative of the market structure of 26 emerging market countries in Europe, Latin America, and the Pacific Basin. It excludes closed markets and those shares in otherwise free markets that are not purchasable by foreigners. The Bloomberg Aggregate Bond Index is an unmanaged market value-weighted index representing securities that are SEC-registered, taxable, and dollar-denominated. It covers the U.S. investment-grade fixed-rate bond market, with index components for a combination of the Bloomberg government and corporate securities, mortgage-backed pass-through securities, and asset-backed securities. The Bloomberg U.S. Corporate High Yield Index covers the USD-denominated, non-investment-grade, fixed-rate, taxable corporate bond market. Securities are classified as high-yield if the middle rating of Moody’s, Fitch, and S&P is Ba1/BB+/BB+ or below. One basis point (bp) is equal to 1/100th of 1 percent, or 0.01 percent. 


Authored by Chris Fasciano, vice president, chief market strategist, at Commonwealth Financial Network®.

© 2026 Commonwealth Financial Network®


Let’s Talk About Your Financial Future

Whether you’re navigating a volatile market or preparing for the future, we’re here to help.

Schedule a Consultation